FERS Retirement Calculator (Free, Uses OPM's Own Rules)
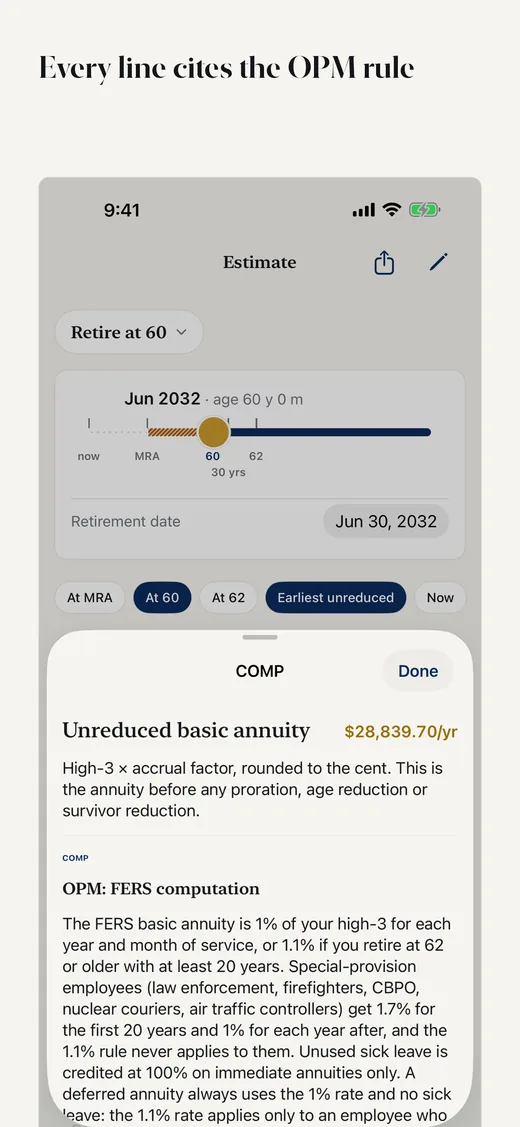
Enter your birth date, service computation date, high-3 and unused sick leave, and the calculator below works out your gross annuity the way an OPM worksheet does, one line at a time, with the handbook rule beside each line. It covers FERS and CSRS, regular and special-provision service, and MRA+10 retirements reduced for age.
Free FERS and CSRS annuity calculator
Gross annuity from OPM's own formulas. No sign-up, nothing stored, nothing sent.
What the calculator computes
It follows the order of OPM's computation worksheet. Service is counted in 30-day months with the retirement day included, and the leftover days are dropped once, after everything is added. Unused sick leave goes through OPM's Chart 2 (2,087 hours equals one year, and a balance between chart entries uses the next higher one). Your minimum retirement age comes from your birth year, the retirement is classified, and the accrual factor is rounded to six places before it is multiplied by your high-3. That rounding matters: on OPM's own Chris Morgan example (high-3 of $53,221 and 31 years 2 months) the six-place factor of 0.311667 gives $16,587.23, while the exact fraction would print $16,587.21. For an MRA+10 retirement the age reduction counts full months under 62 on the day the annuity starts, so a partial month is not counted.
The calculator is tested against the worked examples in OPM's handbook and the other published figures in High Three's golden table, plus 600 randomized cases compared with a separate reference implementation of the same rules. If you want to see a result with a known answer, use the "Lea Williams" button under the form: it loads OPM's MRA+10 example and returns $10,181.11 a year.
What it leaves out, and what the app adds
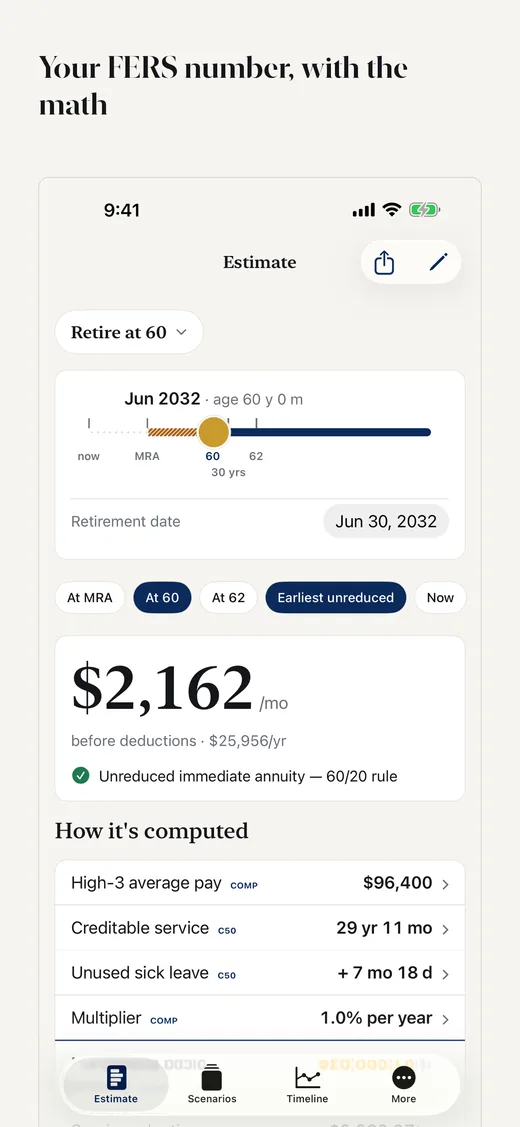
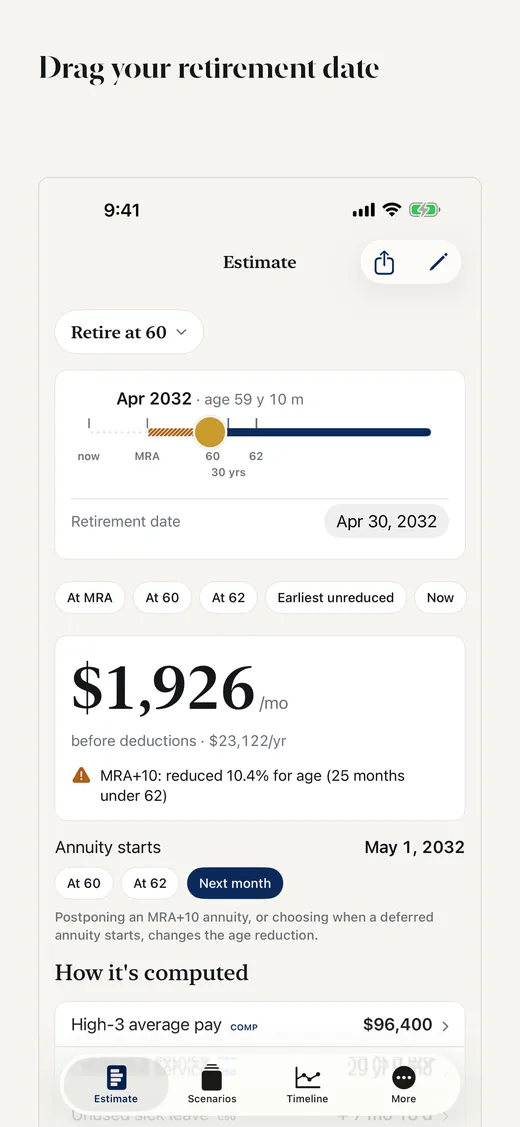
This page gives the gross basic annuity for one period of service. It does not apply a survivor election, the FERS annuity supplement, cost-of-living adjustments, health insurance premiums or taxes, and it does not handle part-time service, deferred retirements or the CSRS Offset. Those are the questions that decide whether a particular retirement date is a good idea, which is why the High Three app for iPhone and iPad computes them from the same inputs: the supplement with the earnings test, partial and full survivor elections, COLA, a year-by-year timeline to age 95 with TSP and Social Security, and three retirement dates side by side. It works offline, needs no account, and full access is a one-time $6.99 purchase with no subscription.

Guides behind the numbers
Each guide works one rule through with figures taken from OPM's handbook, so you can check the calculator against the source.
- MRA+10 retirement: how the 5% per year reduction works with OPM's Lea Williams example and the 20-years-at-60 exception.
- The FERS supplement and the $24,480 earnings test with the $1-for-$2 reduction worked out.
- The 2,087-hour sick leave chart reproduced in full.
- What counts in your high-3 and what does not.
- FERS vs CSRS: the formulas side by side with the 80% cap and special provisions.
Frequently asked questions
What is the high-3?
The high-3 is your highest average basic pay over any three consecutive years of service, and it is the dollar figure your annuity is a percentage of. Basic pay includes locality pay; overtime and bonuses are not part of it. OPM averages the actual pay rates across 78 pay periods, so the calculator asks for the number you expect rather than guessing one. The high-3 guide shows what counts and how to project it forward.
How is sick leave counted?
Unused sick leave at retirement adds time to the service used in the computation, never to the service used for eligibility and never to the high-3. OPM converts hours to months and days with Chart 2, where 2,087 hours is one year: 1,500 hours is not on the chart, so the next higher entry applies and the credit is 8 months 19 days. FERS employees get full credit for retirements on or after January 1, 2014. See the sick leave chart guide.
What is MRA+10?
MRA+10 is a FERS retirement at your minimum retirement age with at least 10 years of service but fewer than 30. The annuity is reduced by 5/12 of 1% for each full month you are under 62 when it starts, unless you have 20 years and start it at 60 or later, and there is no FERS supplement. Your MRA is between 55 and 57 depending on your birth year. The MRA+10 guide works OPM's example through to the cent.
Who gets the FERS supplement?
The supplement, which stands in for Social Security until age 62, is paid to FERS retirees whose annuity is unreduced (including the 30-years-at-MRA and 60-with-20 cases), to special-provision retirees from retirement, and to early (VERA or DSR) retirees from their MRA. It is not paid on an MRA+10 retirement, and it stops when you reach 62. The amount is your Social Security estimate at 62 times your FERS civilian years over 40, and the earnings test can reduce it. The supplement guide has the formula.
Is this affiliated with OPM?
No. High Three is not affiliated with OPM or any federal agency. It uses the rules OPM publishes, links to the OPM page for each line, and gives estimates. Your agency's HR office and OPM compute your actual annuity, so confirm any decision with them.
Does the app need an account?
No. The High Three app has no account and no subscription, runs offline, and keeps what you enter on your phone. The free version covers eligibility and a gross annuity for one scenario; full access is a one-time $6.99 in-app purchase. This website calculator keeps nothing at all: it runs in your browser and nothing you type is sent anywhere.